VIETNAM CHAMBER OF COMMERCE AND INDUSTRY
Liên Đoàn Thương Mại Và Công Nghiệp Việt Nam
Fri, Nov 20, 2026, 15:17:00

Vietnam's real estate market has expanded rapidly but continues to face challenges related to prices, supply, credit and transparency. Ensuring its sustainable development, curbing speculation, protecting homebuyers, and maintaining capital flows to production and business activities will require coordinated policies tailored to individual market segments and stages of development.
The country's real estate market has made significant progress over the past decade, but ensuring stable, transparent operations and balancing the interests of market participants will require a comprehensive and coordinated policy framework rather than isolated regulatory measures.
Market volatility, particularly sharp price increases, has repeatedly reignited debate over the sector's role in the economy. Issues such as speculation, price manipulation, capital flowing into real estate instead of production and business activities, and a lack of transparency frequently come under scrutiny.
However, the real estate sector cannot be viewed separately from the broader level of economic development. Markets that developed ahead of Vietnam, including Singapore, Australia, Japan and China, have also experienced periods of volatility and even crises. The 2008 global financial crisis was a prominent example, with its underlying causes rooted in the U.S. housing market and financial products linked to real estate.

This demonstrates that no real estate market is entirely free of shortcomings. The key challenge is to establish regulatory mechanisms suited to each country's development conditions and economic and social characteristics.
After around 35 years of developing a market-oriented economy, Vietnam's real estate sector has undergone substantial changes. Nevertheless, further institutional reforms are needed to make the market more professional and sustainable, ensuring that all participants enjoy the benefits of market activity while fulfilling their respective responsibilities.
Tax and credit policies should be tailored to individual segments
One issue under consideration is the introduction of property taxes, particularly for individuals owning multiple houses or plots of land, or purchasing a second or third property.
Under this proposal, property taxes could be introduced gradually, with flexible calculations that distinguish between different ownership circumstances. For example, properties acquired through inheritance could be subject to separate consideration, taking into account individual circumstances and cultural traditions.
Regarding personal income tax on real estate transfers, one proposal is to calculate tax based on the length of time an asset has been held. The longer the ownership period, the lower the applicable tax rate could be, with reductions applied according to an appropriate progressive schedule. This approach would distinguish long-term investment from short-term trading, while tax rates would need to be carefully calibrated to ensure practical implementation.
In the credit sector, classifying real estate according to its intended use is considered necessary. Commercial housing, social housing, resort properties, industrial and agricultural real estate, as well as social infrastructure projects such as healthcare and education facilities, should not be subject to a uniform lending framework.
Each segment has different characteristics, capital recovery periods and economic impacts. Credit policies should therefore introduce specific incentives or controls for each category, helping to contain risks while maintaining funding for sectors with genuine development needs.
Similarly, mortgage interest rates could be differentiated according to borrowers' profiles and intended property use. First-time homebuyers, particularly those purchasing social housing or affordable commercial apartments, could be considered for more favorable lending rates than buyers of conventional commercial housing.
For real estate developers, stricter financial capacity requirements should be introduced to prevent projects from relying excessively on borrowed capital. Monitoring financial leverage, particularly among listed companies, is important to reduce the risk of cascading corporate failures and their potential impact on the broader market.
Expanding supply and regulating investment and business activities
Alongside tax and credit policies, supply is considered one of the key factors in stabilizing the real estate market.
To curb speculation, price manipulation and unjustified land price surges, housing and real estate supply must be expanded regularly in line with actual demand. Accelerating project appraisal and licensing procedures must go hand in hand with strict compliance with laws and planning regulations.
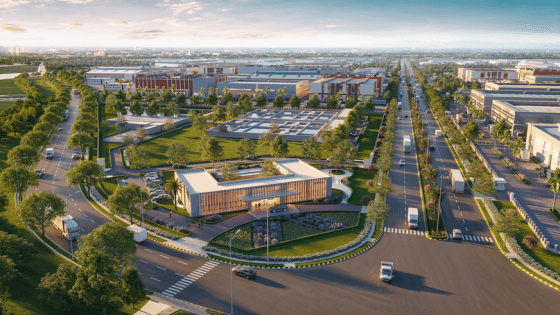
One proposed approach is to prioritize the development of satellite cities, with dedicated land reserves and housing supply plans tailored to local needs. Rather than licensing fragmented, small-scale projects, authorities could encourage large-scale developments with integrated planning for infrastructure, transport, residential areas and public amenities. These projects could subsequently be divided into different zones, allowing multiple developers to participate while maintaining consistency with the overall master plan.
Land subdivision and plot sales should be tightly controlled, particularly in cases that fail to meet planning and infrastructure requirements. Such activities affect not only the urban landscape but also technical infrastructure systems, population density and the quality of the living environment.
In particular, authorities should curb the widespread licensing of land subdivision projects disguised as homestay or farmstay developments that lack a sufficient legal basis or are inconsistent with approved plans. Subdivided plots left vacant not only waste land resources but also undermine the organization of urban development.
For off-plan housing, developers' financial capacity must be subject to strict scrutiny. One proposed measure is to establish clear rules governing the use of advance payments from customers, ensuring that the funds are directed towards project implementation and preventing misuse that could lead to construction delays or stalled developments.
Conditions for launching property sales should also be strictly monitored, alongside bank guarantee mechanisms and clear accountability for parties involved if developers fail to meet their obligations. These measures are seen as important safeguards for homebuyers while helping screen out developers lacking the capacity to deliver projects.
For social housing, one notable proposal is to study a mechanism allowing local authorities to buy back apartments once the legally stipulated restriction period on transfers has expired. The units could then be returned to the social housing stock and allocated to other eligible households, helping prevent the exploitation of housing policies for speculative gains.
At the same time, the allocation of land for social housing within commercial housing projects should be reconsidered. Instead of requiring a fixed proportion of land to be reserved within each individual development, authorities could consider planning separate social housing areas to ensure coordinated development and a fairer distribution of housing obligations.
This issue should be addressed as part of a broader, long-term housing development programme rather than through a series of individual projects.
For resort real estate, another proposal is to consider allowing foreign nationals to own condotel apartments under specific regulatory conditions, including limits on the length of stay and obligations towards property operators. The aim is to broaden the customer base and attract additional international capital while ensuring effective management and security.
Improving transaction mechanisms and raising brokerage standards
A sustainable real estate market requires not only adequate supply and capital flows but also a transparent transaction system that protects the rights of all parties involved.
Accordingly, the buying and selling process should be clearly regulated, from deposits and purchase contract signing to property handover and the issuance of ownership certificates. Developers' obligations to provide information, as well as buyers' rights and responsibilities, should be clearly defined to prevent customers from being denied access to essential information or placed at a disadvantage when disputes arise.
Alongside improvements to transaction procedures, the market also needs a more diverse range of real estate financial products. Such instruments could provide additional funding channels for businesses while offering investors more choices, rather than concentrating all capital flows in direct property purchases and sales.
Another issue is real estate brokerage. Although the Law on Real Estate Business already contains provisions governing the sector, further improvements to the legal framework for the profession remain necessary.
Regulations should provide greater clarity on professional qualifications, occupational responsibilities, standards of professionalism and the rights of individual brokers and brokerage companies. In practice, disputes over commission fees, service contracts and the respective responsibilities of brokers and businesses can still arise. Without clear dispute resolution mechanisms, not only can the parties directly involved suffer losses, but the reputation of the brokerage profession can also be damaged.
Improving brokerage standards therefore requires more than tightening licensing requirements or monitoring business activities. It also involves establishing mechanisms to protect the legitimate rights and interests of those working in the profession.
Overall, the challenges facing Vietnam's real estate market cannot be addressed through a handful of isolated measures. Taxation, credit, planning, supply development, developer oversight, transaction regulations and brokerage activities are all closely interconnected.
A transparent and stable market requires a comprehensive, coordinated regulatory framework that is appropriate to each stage of development. More importantly, policies must strike a balance between controlling risks and curbing speculation, while maintaining investment and business activities and meeting people's housing needs.