VIETNAM CHAMBER OF COMMERCE AND INDUSTRY
Liên Đoàn Thương Mại Và Công Nghiệp Việt Nam
Fri, Oct 02, 2026, 23:58:00

In the first six months of 2026, CTG was among the group recording outstanding business results, with profit growth of over 36.7% compared to the same period last year.
Improved Credit Growth
In Q3/2026, CTG's credit growth is forecast by MBS to reach around 10%. Alongside this, profit for this quarter will be lower than the previous quarter, forecast at approximately VND 10,843 billion, but still representing a strong year-on-year increase of 27.4%. The expansion of lending to major projects—including large-scale projects serving the 2027 APEC Summit—expected to accelerate disbursement in the second half of 2026—is the driving force for this bank's credit growth. CTG has a deposit-credit gap, with Q3 deposit growth forecast at around 9%, though it will continue to be driven by the large corporate and FDI customer segments.
CTG's credit growth momentum is expected to improve in the second half of this year compared to the level seen in the first half of 2026. However, the overall credit growth rate for the full year will slow down compared to 2025.
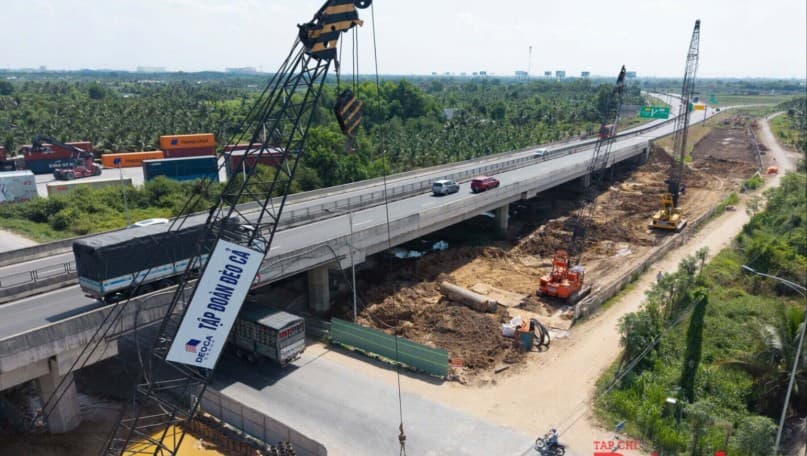
According to Vietcap, 35 key national infrastructure projects under the special credit limit mechanism are factors that could provide additional room for CTG's credit growth. However, analysts believe this is a factor creating upside potential rather than a core driver in the baseline scenario, as CTG is still in the initial contact phase and has not yet received official loan applications.
"With its leading position in the infrastructure sector and close relationships with large corporations and project management boards under the Ministry of Construction, CTG will be one of the main beneficiaries of the Government's continued push for infrastructure investment," Vietcap assessed.
NIM Improvement
CTG's Net Interest Margin (NIM) in Q3/2026 is also forecast to continue its positive recovery, reaching 2.7%, up 14 basis points year-on-year, despite a slight decrease of 5 basis points quarter-on-quarter. Here, NIM improvement comes not only from positive deposits, CASA sources, and lending expansion, but importantly, the bank's cost of funds (COF) is supported by policy drivers. These include liquidity support, funding sources for LDR calculation, and crucial backing for the system's medium- and long-term lending capacity derived from the amended regulations of Circular 22/2019/TT-NHNN.
Full-year 2026 NIM is forecast to reach 2.85%, an increase from 2.62% in 2025, and is expected to continue rising to 2.90% in 2027 and 2.95% in 2028. This is a positive NIM ratio when compared within the Big 4 group and in the context of interest rates trending high, with intensified deposit competition across all funding channels—savings, bonds, and certificates of deposit—a competition that VietinBank is not sitting out.
Additionally, the bank's provisioning costs are forecast to decrease by 45.8% year-on-year and 40.0% quarter-on-quarter, as asset quality remains secured. By the end of Q2/2026, CTG had actively provisioned resources for risk resolution. The bank's non-performing loan (NPL) coverage ratio reached 134% and is still maintaining a buffer around the 150% mark.
Promising Factors Not Yet Forecasted
Vietcap estimates that CTG's pre-provision profit in 2026 could reach VND 73,711 billion, up 21.3% compared to 2025. Profit after tax and minority interests (PATMI) is projected at VND 41,595 billion, up 20.2%. The forecast profit does not yet include any profit from the transfer of CTG's VietinBank Tower project. In other words, among CTG's stated favorable conditions, the sale of VietinBank Tower—as informed by the bank's management at the end of Q2, though not yet detailed—deserves to be expected as a massive net profit item that could radically alter the profit forecast for this full year, or next year, towards a sudden breakthrough.
Furthermore, according to Decision 40/2026/QD-TTg, CTG is still in the waiting period for a plan to increase State ownership to a minimum of 65% of charter capital, up from the 64.46% currently held by the SBV. This plan is expected not to stop at the minimum level but to go higher, ensuring the goal of balancing ownership ratios in accordance with State regulations, alongside the ratios of major shareholders such as MUFG Bank, the CTG Trade Union, etc. This plan could also propel capital increase or ownership restructuring plans, thereby supporting the bank's capital adequacy ratio (CAR) and credit growth capacity. It could also spark a new wave of positive revaluation for the bank, as CTG stock is currently considered to be relatively undervalued. CTG is currently trading at around 1.27x P/B, lower than BID's 1.44x and VCB's 2.03x, and also lower than CTG's own 5-year average P/B of 1.37x, according to MASVN.
Vietcap also values CTG at a very attractive level, with a 2026 projected ROE of 21.3% but a 2026 projected P/B of only 1.2x. Simultaneously, it maintains a positive view that CTG will continue to achieve outstanding business results compared to other banks in terms of NIM, asset quality, and overall profitability, thereby supporting the stock being revalued higher.
However, analysts still note risk prospects that could arise from higher NPL ratios and lower credit growth—risk assumptions that need to be factored in amid an interest rate environment coupled with inflationary pressures, where any fluctuations could affect both loan absorption capacity and repayment capability. Even so, in reality, these assumptions would hardly impact the financial strength and prospects of banks with advantages, solid foundations, and persistently maintained operational efficiency and asset quality like VietinBank.