VIETNAM CHAMBER OF COMMERCE AND INDUSTRY
Liên Đoàn Thương Mại Và Công Nghiệp Việt Nam
Fri, Oct 23, 2026, 14:53:00
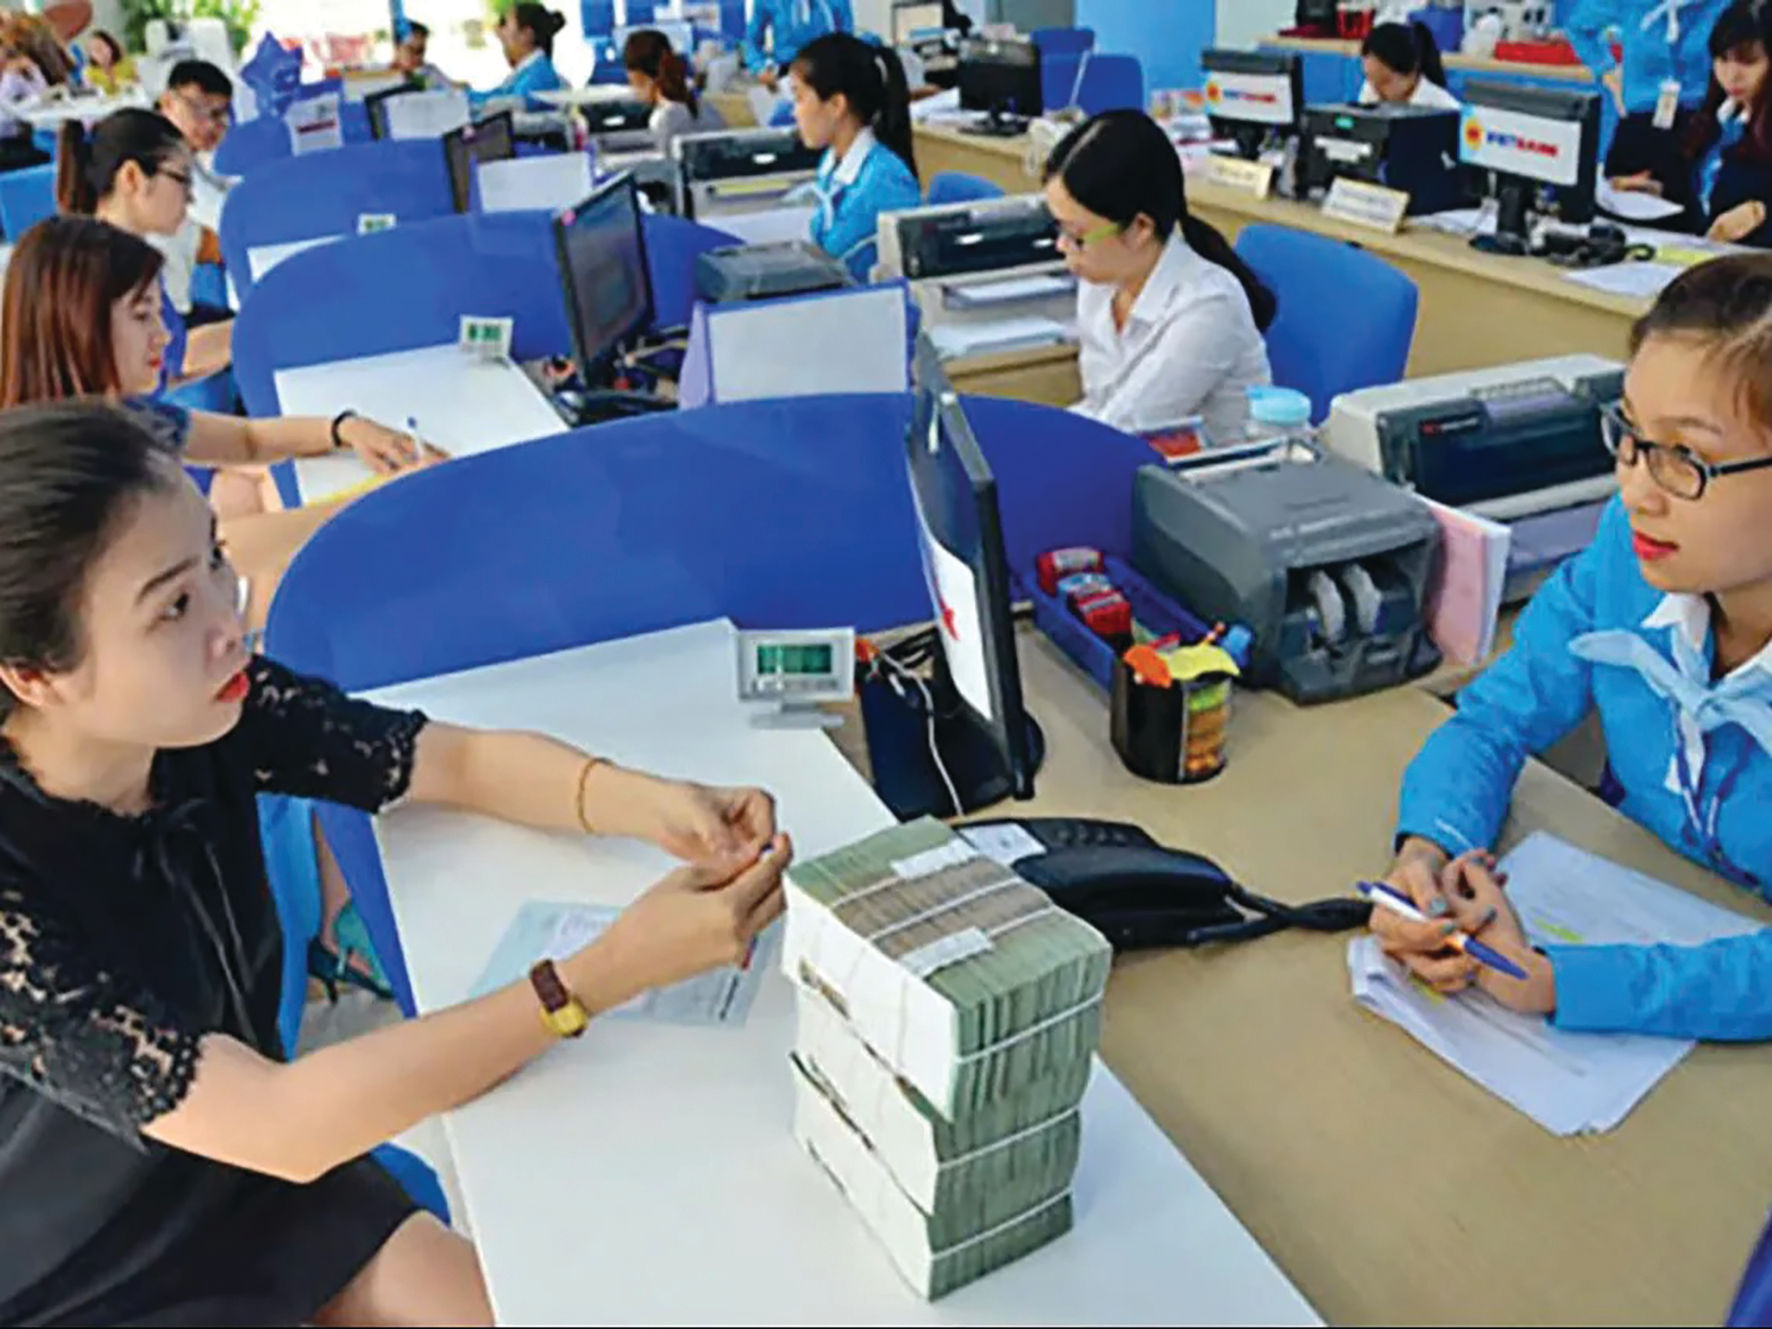
Banks will need to make efforts to cut and optimize operating costs to implement preferential loan packages.
According to the Governor of the State Bank of Vietnam (SBV), Phạm Đức Ấn, if deposit interest rates do not fall, there is no basis for reducing lending interest rates.
Orientation to cut lending interest rates
"This is not the first time the SBV has issued such directives (regarding the orientation to lower interest rates), but rather many times before," stated SBV Governor Phạm Đức Ấn during a working session with leaders of credit institutions regarding interest rate reduction.
Recalling back in April 2026, SBV Governor Phạm Đức Ấn held a meeting with 46 banks, all of which committed to lowering interest rates. At that time, the deposit market witnessed the highest interest rate levels since 2022, nearly touching the 10%/year mark for certain tenors. Banks fulfilled their commitments to lower interest rates, with rates for terms of 6 months or longer at several major credit institutions dropping to 7.4%–7.6%/year.
However, against a backdrop of global economic volatility—where many countries raised interest rates alongside inflation risks driven by Middle East conflicts, escalating energy prices, and rising commodity costs—pressure mounted on capital flows and investment. At the same time, demand for capital, particularly medium- and long-term capital for investment growth cycles, increased sharply. As a result, although the USD/VND exchange rate remained stable, input interest rates across the banking system eventually established a new baseline after a period of suppression.
The SBV Governor's new directive, following instructions from the Government on lowering lending interest rates, continues to focus on the key "hinge" of balancing capital sources with capital deployment: lower deposit interest rates provide the foundation for reduced lending rates.
Following the directive, banks including BIDV, Vietcombank, Agribank, Sacombank, and OCB have implemented lending rate cuts. Maybank Securities noted that with top leadership guidance, lending rates may have peaked and are expected to gradually decline. However, in the short term, the extent of the reduction will vary across sectors, with most support concentrated on priority fields. Banks will need to make efforts to cut and optimize operating costs to roll out preferential loan packages targeted at specific customer groups. The specific eligibility conditions for these loan packages have not yet been announced.
Where to cut input costs?
In the long run, lending interest rates can only drop across the board and remain sustainably at reasonable levels—around 7%–10%/year—if input capital costs are also significantly reduced. To balance input costs, Maybank experts recommend addressing three key areas:
First, address leakages that deplete money supply.
Second, accelerate and expand refinancing programs for banks at reasonable capital costs, enabling them to lend at lower interest rates to targeted and priority projects and sectors.
Third, construct a framework for capital mobilization and supply for development, where the Government and banks play the leading role in sourcing external capital to serve growth. The Government needs to promptly supply capital for strategic projects and target groups through refinancing programs.
In Official Dispatch No. 9608/NHNN, the SBV required banks not to engage in deposit rate races, to reduce deposit interest rates by at least 50 basis points for terms of 6 months or longer, and to lower lending rates by 150–200 basis points for production sectors and priority groups. Furthermore, the SBV issued clear regulations on credit growth, capital flow controls, large customer outstanding balances, shareholder groups, and dividend payouts. These represent visible and controllable "leakages" when regulators demonstrate resolve and enforce sanctions directly linked to bank profitability. Consequently, the quality of control is expected to depend on effective inspection and oversight processes.
Additionally, banks themselves are planning to accelerate non-deposit capital additions—a solution that fulfills special LDR requirements under Circular 50/2026/TT-NHNN while securing lending cash flows at appropriate costs.
According to estimates by SSI Research, eight banks—NCB, BIDV, Vietcombank, HDBank, VPBank, MB, PVComBank, and MSB—are planning share issuances from Q4/2026 through 2027, with an estimated total value of 143,830 billion VND (equivalent to approximately 5.4 billion USD). If successfully executed, the equity capital of these listed banks could rise by approximately 6.9%. Increasing equity capital helps banks achieve two objectives: gaining scale to diversify funding sources through certificates of deposit, bonds, and international capital markets; and expanding headroom for credit growth, enhancing risk absorption capacity, and funding technology and digital transformation initiatives.
Thus, the measures required to resolve capital supply issues will depend heavily on decisive action by banks across their mobilization plans, laying the groundwork for substantive lending rate cuts.