VIETNAM CHAMBER OF COMMERCE AND INDUSTRY
Liên Đoàn Thương Mại Và Công Nghiệp Việt Nam
Mon, Oct 19, 2026, 16:55:00
The selling pressure from foreign investors has heavily impacted the VN-Index. So, how can this capital flow be brought back to the market?
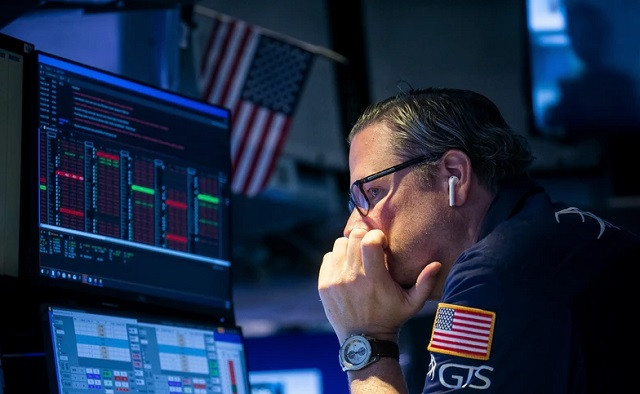
SSI Research expects disbursement flows following FTSE Russell's roadmap to halt the net outflow in the early months of 2027. (Photo: VNA)
Foreign investors net selling
At the close of the October 15 trading session, the HOSE floor had 164 gainers and 153 losers, with the VN-Index dropping 6.52 points (-0.38%) to 1,698.35 points. Total trading volume reached 684.8 million units, valued at VND 15,043 billion, up 17.26% in volume and 9.54% in value compared to the previous day.
Despite continuous capital withdrawals since Vietnam's stock market was upgraded in September, foreign selling pressure shows no signs of abating. Including the October 15 session, this group extended its selling streak to 17 consecutive sessions, withdrawing nearly VND 25,000 billion from the market. This marks the longest net-selling streak since late October 2024.
According to HOSE data, foreign investors have withdrawn a total of VND 116,000 billion since the beginning of the year, showing that despite the upgrade, foreign capital flight has not stopped.
Reports from several securities firms indicate that this capital flight is mainly driven by global capital rotation trends. International capital is leaving emerging markets for regions offering superior profit growth stories, such as tech stocks in various other countries. However, capital outflow pressure in Vietnam remains lower compared to other Asian stock markets like South Korea, Taiwan, and India.
A report from MBS Securities highlights that net selling pressure is linked to US government bond yields exceeding 5%, the Fed continuing its monetary tightening, and a strong US dollar. This reduces the attractiveness of emerging markets, including Vietnam.
Additionally, the net selling streak involves active funds taking profit to rebalance portfolios after months of buying ahead of the market upgrade news. Following 17 consecutive sessions of net withdrawals, foreign ownership on HOSE has fallen to around 13%, significantly lower than the 15% recorded during the same period last year.
Expectations for foreign capital to return
In its strategy report forecasting the market for 2027, SSI Research expects disbursement flows according to FTSE Russell's roadmap could stop the outflow momentum in the early months of 2027. According to SSI, approximately USD 2.7 billion in passive capital tracking FTSE indices could be disbursed next year, equivalent to 0.7% of current market capitalization and equal to 70% of foreign net selling in the first 9 months of this year.
In the short term, SSI Research notes that the Vietnamese stock market still faces correction risks before recovering in late 2026 and early 2027. Supported by growth-orientated economic policies, the Government continues to set a double-digit GDP growth target for 2027. Infrastructure investment remains a key growth driver as major projects launched in 2025–2026 transition into construction phases, alongside potential starts for projects like elevated inland rail lines.
Furthermore, inflationary pressure is forecasted to cool down due to oil prices returning to normal as global supply recovers. With limited room for further interest rate hikes narrowing the gap between credit growth and deposits, foreign capital will have additional motivation to consider returning to the market.
Although strong foreign net buying does not always trigger immediate market rallies—due to the lag effect of money flow spillover—foreign trading activity remains a key indicator. Foreign capital often acts as an initial catalyst for both active foreign funds and domestic individual investors.
Historically, SSI Research notes that foreign net buying usually accompanies strong broad-based market rallies, such as in 2017 to early 2018 and during various bottoming or recovery phases. This highlights a synchronized timing effect. However, upcoming FTSE disbursements from September 2026 through 2027 could provide stronger support if aligned with cooling interest rates and improved investor sentiment.
In the long run, inclusion in MSCI's Watchlist serves as a key supporting driver for Vietnam's stock market. Vietnam currently meets 10 out of 18 market accessibility criteria set by MSCI and continues to make progress on the remaining ones. Notably, plans to operate the Central Counterparty (CCP) clearing system in early 2027, along with developing omnibus accounts to meet specific MSCI requirements, are crucial milestones that could significantly enhance Vietnam's chances of joining the Watchlist. These factors will be instrumental in bringing foreign capital back to the market in the coming period.