VIETNAM CHAMBER OF COMMERCE AND INDUSTRY
Liên Đoàn Thương Mại Và Công Nghiệp Việt Nam
Fri, Oct 02, 2026, 23:58:00

Private enterprises are no longer seen merely as market participants but as key strategic partners working alongside the State to drive economic development.
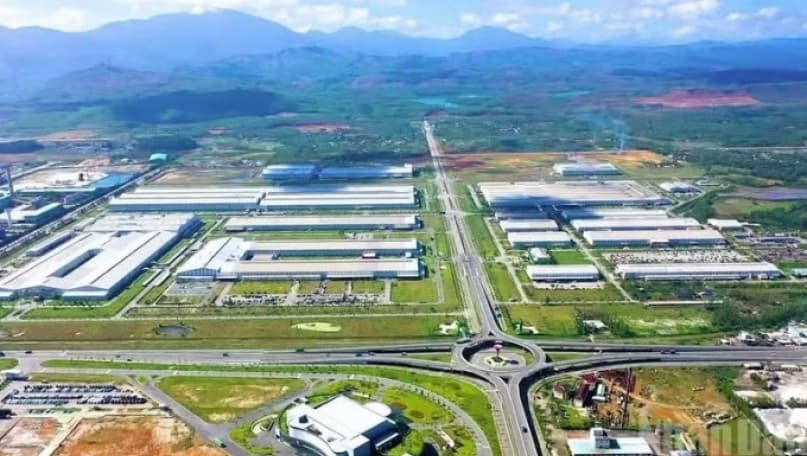
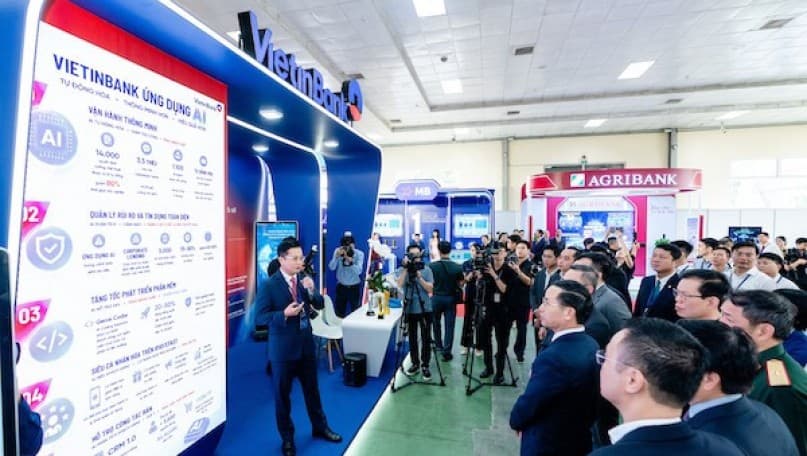
At an investment promotion conference held on 29 September, Vietnam’s Ministry of Construction outlined plans for expressway development from 2026 to 2030. The event aimed to raise funding, expand economic horizons, and establish a modern, integrated national motorway network.
Public capital as an essential seed one
The Ministry of Construction unveiled a priority portfolio of 29 public-private partnership (PPP) expressway projects slated for 2026–2030, with total estimated capital requirements of around VND 922.8 trillion.
Minister of Construction Tran Hong Minh urged domestic conglomerates and international investors to proactively review and apply for these high-priority schemes. He also called on major commercial banks, including BIDV, VietinBank, Vietcombank, Agribank, MB, and Techcombank, to structure long-term credit facilities at competitive interest rates to establish a stable financial foundation for the pipeline.
According to Nguyen Thi Thu Ha, Deputy Head of the PPP Office under the Ministry of Finance’s Public Procurement Agency, 30 PPP projects have received formal policy approval since the PPP Law came into force, with 12 contracts signed to date. These megaprojects are primarily concentrated in transport infrastructure, representing a total investment of roughly VND 1.3 quadrillion.
Within this framework, 24 Build-Operate-Transfer (BOT) schemes account for approximately VND 390 trillion in capital expenditure. Public investment contributed around VND 103 trillion, while private investors contributed VND 297 trillion.
Ms Ha highlighted that every single dong of public capital invested successfully leveraged nearly three dongs of off-budget funding, demonstrating the vital role of public funds as "seed capital" in PPP ventures.
However, the Ministry of Finance acknowledged that financing transport infrastructure under PPP models still faces persistent bottlenecks, particularly concerning capital sourcing and financial risk management.
A primary structural weakness is that project debt relies predominantly on commercial banks, which offer short loan tenures and elevated interest rates that clash with the long pay-back horizons of infrastructure assets. Meanwhile, long-term capital channels, such as project bonds, infrastructure investment funds, and specialized institutional lending, remain underdeveloped.
Compounding these issues, some projects involving BOT projects signed prior to 1 January 2021, and lingering disputes dating back to 2017, have eroded the confidence of institutional investors and credit institutions in transport PPPs.
Despite the introduction of risk mitigation frameworks, revenue risk remains a serious hurdle. Realized traffic volumes falling short of forecasts, or delayed tariff adjustments, can severely undermine a project's financial viability. Land clearance delays and building material supply bottlenecks also continue to threaten project feasibility.
Regarding Build-Transfer (BT) contracts, the sheer scale of investment coupled with land-swap payment mechanisms creates complex challenges around land valuation, public transparency, and preventing the loss of public assets.
Given these real-world pressures, Ms Ha stressed the need for far more rigorous project appraisal prior to tendering under PPP structures. Financial viability must be guaranteed to insulate projects against demand risk and debt-servicing failures during operation.
For essential infrastructure schemes that lack commercial viability, the Ministry of Finance representative proposed delivering them through traditional public investment. Once constructed, the Government could then grant tolling concessions to private operators through Operate-Maintain (O&M) contracts or other suited models.
One financial model does not fit all
Offering a market perspective, Mr Ho Minh Hoang, Chairman of De Ca Group, a long-standing player in Vietnam’s transport PPP sector, welcomed the policy of encouraging private capital into infrastructure.
He pointed out that Resolution 68/NQ-TW issued by the Politburo signals a fresh approach to the private sector. Private enterprises are no longer seen merely as market participants but as key strategic partners working alongside the State to drive economic development.
However, Mr Hoang cautioned against applying a rigid capital structure across all PPP projects. Depending on commercial dynamics, some projects require no public investment at all, while others may require a 20%, 30%, or tailored public contribution. In certain cases, Government involvement might be limited to site clearance or funding connecting links, while other schemes could draw from multi-party funding pools. Capital structures must be custom-built based on the specific risk profile and cash-flow generation of each project.
From an advisory perspective, Nguyen Viet Long, Deputy General Director of EY Vietnam, emphasized that bankability and investment efficiency require simultaneous focus on four pillars: the regulatory framework, project preparation quality, access to capital, and construction risk management.
Mr Long noted that Vietnam’s PPP legal landscape has matured steadily, while traffic growth across the expressway network shows positive momentum. This is critical, as traffic risk represents one of the largest variables for toll-road PPPs, impacting revenue visibility and financial stability.
Crucially, project preparation must meet institutional credit underwriting standards from day one, rather than merely satisfying regulatory submission requirements. Diversifying capital sources is equally vital. Mr Long highlighted that Vietnam’s corporate bond market currently stands at only 10 - 11% of GDP, substantially lower than regional peers like South Korea or Malaysia, leaving ample room for growth.
While corporate bonds cannot replace credit facilities during the high-risk construction phase, they serve as an ideal long-term refinancing tool once assets are operational and generating steady toll revenues.
Furthermore, a mechanism should be created to attract institutional investors, such as pension funds, insurance companies, and long-term development funds, into the infrastructure capital market. Finally, controlling construction risks, particularly cost overruns and land acquisition delays, must be carefully factored in during early-stage project preparation.